


7 Saving methods you should know

At a glance
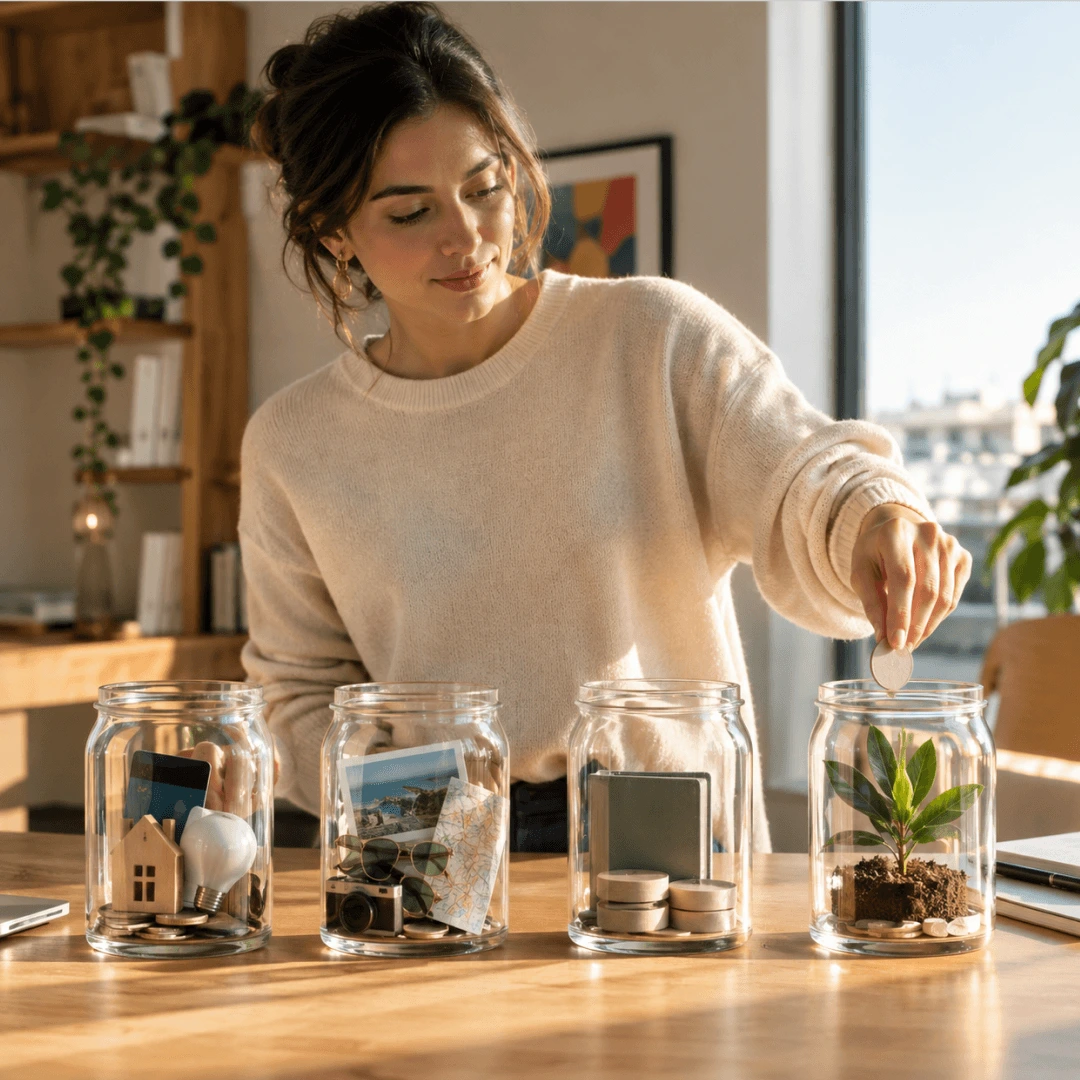
A savings method is a straightforward system for allocating your income between expenses, savings and goals. It is used by people who want to save regularly, rather than relying on whatever money is left over at the end of the month.
• Using savings methods can help you organise your finances, control your spending, and set priorities.
• It is more realistic to save consistently if you choose a method that is suited to your income, expenses, and goals.
• With Carregosa NextGen, you can develop consistent financial habits and plan for the future with confidence.
Do you want to increase your savings rate but aren’t quite sure where to start? In this article, we’ll introduce you to seven effective saving methods you may not yet be familiar with, from the 50/30/20 rule to the so-called "envelope method”.
Throughout the article, we answer the following four questions: how does each method work? What are the differences between them? How do you choose the one that suits your income? Where should you put your money once you’ve saved it?
1. The 50/30/20 rule: dividing your income into three parts
The 50/30/20 rule involves dividing your monthly net income into three categories: 50% for essentials, 30% for discretionary spending, and 20% for savings, investments, or debt repayment. This is one of the simplest methods because you don’t need to track every single expense.
Imagine you earn €1,500 net per month. According to this rule, you would allocate €750 to essential expenses such as rent, food, transport, and bills, €450 to non-essential expenses such as eating out, leisure activities and shopping, and €300 to savings, investments or debt repayment. Unlike the money you keep in savings, the portion you allocate to investment is subject to risk, including the possibility of losing capital.
However, bear in mind that the 50/30/20 figures are not set in stone. They provide a structure to help you understand your spending and where you can make adjustments.
How to use this rule: work out your monthly net income and see how much you spend on average in each of the three categories. If 20% seems too ambitious, start with a lower percentage.
2. The envelope method: setting a limit for each spending category
With the envelope method, a fixed amount is allocated to each spending category, which is then treated as a monthly limit. This method is best suited to those who want to know how much they can still spend in each area at any time during the month.
Money used to be put into physical envelopes, but nowadays you can apply the same principle using bank accounts, sub-accounts, spreadsheets or financial management apps.
For example, you could allocate €250 to food, €100 to leisure activities, and €75 to shopping. If you spend the €100 allocated for leisure activities before the end of the month, you can either wait until the next month or transfer money from another category. Be aware of the impact that this decision will have.
How to use this rule: identify the three to five categories in which you spend the most money, set a realistic monthly limit for each category, and start by using a digital version of this plan.
3. "Pay yourself first”: save at the start of the month rather than at the end
The "pay yourself first” method involves transferring the amount you wish to save on the day you receive your salary, before paying any other bills or expenses. Saving no longer depends on whatever money is left over at the end of the month; it is a fixed commitment.
For example, if you earn €1,500 and decide to save €150, you can arrange for an automatic transfer to take place on your pay day, from your current account to a separate savings account or fixed-term deposit account. Please note that these accounts have their own terms and conditions. You then have to manage the rest of the month with the remaining €1,350.
How to use this rule: set up an automatic transfer to transfer a set amount of money each month, and then increase this amount once the habit is established.
"The most effective method is almost always the one that requires the least discipline on a daily basis. Automating a payday transfer means you only have to make one decision, whereas other methods require you to make thirty decisions a month.” — Miguel Ricon Ferraz, Head of the Investment Advisory Service at Banco Carregosa.
4. Zero-based budgeting: assigning a purpose to every euro
With zero-based budgeting, the purpose of every euro you receive is assigned at the start of each month. There is no surplus income: any money not spent on expenses is either saved or put towards a specific goal.
Imagine you earn €1,800 per month. You could allocate €800 to housing and bills, €250 to food, €150 to transport, €200 to leisure activities, €250 to savings, and €150 to other expenses. If you have money left over in a category, you can either transfer it to a savings goal or adjust your next budget.
Although this method requires more monitoring than the 50/30/20 rule, it can be particularly useful for managing several different expenses.
How to use this rule: make a list of your monthly income and all anticipated expenses. Allocate each amount to a specific category and review your budget throughout the month.
5. The Kakeibo method: reflect before you spend
Created in 1904, Kakeibo is a Japanese method of financial organisation that combines the manual recording of expenses with a moment of reflection before each purchase. Rather than simply looking at how income is allocated, it looks at spending behaviour.
Kakeibo encourages you to ask yourself questions such as: "Do I really need this?”, "Can I manage without this purchase?”, and "What could I do differently next month?”.
For example, you might realise that you spend €80 a month on food deliveries. Rather than simply reducing this amount, Kakeibo helps you to understand why you make these purchases and to come up with practical solutions, such as preparing meals in advance.
How to use this rule: keep a record of your spending for a whole month. Then, at the end of each week, look at where you spent money, ask yourself if it was necessary, and think about whether you could have avoided it.
The article dedicated to the method covers the four traditional Kakeibo categories and provides a complete, step-by-step guide and a monthly record sheet. Find out how the Kakeibo method works, step by step.
Suggested reading
If you’re interested in understanding what influences your spending habits, it’s worth reading our insights into the psychology of money.
6. The 70/20/10 rule: a simpler breakdown than the 50/30/20 method
The 70/20/10 rule involves allocating 70% of your income to everyday expenses, 20% to savings or investments, and 10% to specific financial objectives, such as paying off debts or funding a short-term goal.
The difference between the two rules lies in the number of decisions involved. The 50/30/20 rule forces you to separate your needs from your wants, whereas the 70/20/10 method combines the two into a single allocation, setting aside a portion for a specific goal.
How to use this rule: define what each of the three categories means to you. If you have debt that you want to pay off, you can direct the 10% towards that goal.
7. The 52-week challenge: saving as a routine rather than as a percentage of your income
The 52-week challenge makes saving a weekly routine rather than something dependent on a percentage of your income. This is the best method for developing discipline, starting with small amounts.
In the traditional version, you start with €1 in the first week, then €2 in the second, €3 in the third, and so on, until you reach €52 in the final week. If you stick to it every week, you’ll have saved €1,378 by the end of the year.
If increasing the amount each week is too challenging, set a fixed weekly amount (such as €10) or a monthly challenge with progressive targets.
How to use this rule: choose a comfortable initial amount, set up automatic transfers and use a separate account to help you stick to your plan.
Which savings method is right for you?
The seven methods address different problems. The table below summarises the rationale behind each method, and the profile to which it is best suited.
| Method | Main principle | Ideal for |
|---|---|---|
| The 50/30/20 rule | Dividing your income into three categories: essentials, discretionary spending, and savings. | Those looking for a simple framework with which to start organising their budget. |
| The envelope method | Setting a fixed limit for each category of expenditure. | Those who want a clear overview of what they can spend in each area. |
| Pay yourself first | Saving at the start of the month before spending any money. | Those who want to get into the habit of saving, rather than relying on whatever’s left over at the end of the month. |
| Zero-based budget | Assigning a purpose to every euro received, without leaving any money unallocated. | Those who like detail and want to control their budget down to the last cent. |
| Kakeibo | Recording expenses, reflecting on every purchase, and reviewing spending habits every month. | Those who want to be more aware of their finances and have control of their spending habits. |
| The 70/20/10 rule | Allocating income between day-to-day expenses, savings, and specific goals. | Those who prefer a straightforward, flexible approach. |
| The 52-week challenge | Saving a progressively increasing amount each week for a year. | Those who want to develop discipline by setting themselves small, regular goals. |
There are three criteria that can help you decide. If your income varies from month to month, it is better to use percentage-based methods than those that set fixed amounts. If the problem is spending money before saving it, the "pay yourself first” method can solve this by setting up an automatic transfer. If you’re struggling to keep track of your spending, try using envelopes or the Kakeibo method, which force you to keep a record. You can also combine methods. For example, you could use the 50/30/20 rule to determine your savings target, and then use the "pay yourself first” method to put this into practice on payday.
What should you do with the money you save?
The way you save money determines how much you set aside, not where you keep it. These are two separate decisions.
The first priority is usually an emergency fund that carries no risk of capital loss and offers quick access. Bank deposits held with authorised institutions in Portugal are covered by the Deposit Guarantee Fund (FGD) up to €100,000 per depositor and per institution.
Once you’ve set up your emergency fund, you can invest the rest of your savings with a longer-term outlook. The logic changes here: funds, ETFs and shares all carry risk, including the possibility of losing your initial investment. The best option for you will depend on your time horizon and risk profile.
Suggested reading
• Emergency fund: how much you should have set aside
• 7 alternatives to a savings account that you should know
• Financial freedom: what it is, how to calculate it, and how to achieve it
Boost your savings with Carregosa NextGen
The right method is one that you can stick to for months on end; it’s not necessarily the strictest one on paper. If you have previously given up on a method, it is worth trying a different one that involves fewer daily decisions rather than trying the same method again and expecting a different outcome.
Founded in 1833, Banco Carregosa is a regulated institution that is subject to supervision by both Banco de Portugal and the Portuguese Securities Market Commission (CMVM). Discover the world of finance and investments with Carregosa NextGen, your go-to source for expert information. Find out what Carregosa NextGen is all about.
If you want to turn your saving habits into a sustainable strategy, contact us to open an account and start building your financial future.
Savings methods: FAQs
In the following section, we address the most frequently asked questions regarding savings methods.
1. What is the best savings method?
There isn’t a single savings method that’s best for everyone. The most suitable method for you will depend on your income, expenses, financial goals and habits. Experiment with different methods to find the one that works best for you.
2. What is the best way to start saving money every month?
Begin by analysing your income and expenses, then set yourself a realistic savings target. Setting up an automatic transfer to a savings or investment account at the start of each month is a great way to turn this goal into a habit.
3. Does the 50/30/20 rule work?
While the 50/30/20 rule can serve as a starting point, it does not need to be applied rigidly. As certain expenses, such as housing costs, can account for a large proportion of your income, you should adapt the budget breakdown to your specific circumstances.
4. What is the difference between the Kakeibo method and the 50/30/20 rule?
The 50/30/20 rule is an allocation method that sets out the percentage of your income that should go towards each type of expenditure. Kakeibo is a method of recording and reflection. It requires you to note down every expense and question it before making it. The 50/30/20 rule tells you how much you can spend, while Kakeibo helps you understand why you spend.
5. How much should I save each month?
There is no set percentage. Although percentage-based methods suggest 20% of your net income, the right amount ultimately depends on your fixed expenses, debts, and objectives. It’s better to set yourself a lower target and stick to it each month, rather than setting yourself a big target that you’ll give up on when things get tough.
6. Is it better to save or invest?
Saving is important for building up a financial buffer to cover unexpected expenses. Investing, on the other hand, can help you grow your wealth in the medium and long term, but it involves risk. When making your choice, you should consider your goals, time horizon and risk profile.
Legal disclaimer: This article has been prepared by Banco Carregosa for information and educational purposes only. Under no circumstances does it constitute an investment proposal, recommendation to purchase, or personalised financial advice. Investing in financial instruments carries risks, as well as the possibility of losing the invested capital. Past performance is no guarantee of future returns. You should consult your account manager or financial advisor before making any financial decisions to assess whether they are suitable for your risk profile and financial objectives.
Pension Savings Scheme
Although nobody can predict the future, it is possible to plan for it.
Learn moreMore solutions

Unit-Linked Insurance
Tax-efficient financial investment solutions tailored to the type of asset.
Explore